The Strategic Mandate: De-risking and Scaling Electric Vehicle Infrastructure Investment Across the Arabian Gulf
The trajectory of global energy markets has fundamentally shifted. For developed economies, this transition was a gradual process; for the nations of the Arabian Gulf—Saudi Arabia, UAE, Qatar, Kuwait, Oman, and Bahrain—it is an urgent, strategic imperative tied directly to national economic diversification and sustainable development goals.
The question for Gulf businesses operating in commercial compounds, industrial hubs like Jubail, or smart urban developments is no longer whether to invest in solar or electric mobility—it is how quickly you can recover your capital and begin treating energy independence as a competitive advantage rather than merely managing it as an overhead cost. Electric Vehicle (EV) infrastructure is the physical manifestation of this strategic pivot. It represents more than just a collection of chargers; it is the foundational utility layer that unlocks massive, untapped market potential across commercial operations, industrial parks, and mixed-use residential compounds.
As major initiatives accelerate, evidenced by mega-projects guiding Vision 2030 development, the scale required for EV charging networks is unprecedented. This shift demands a specialized understanding of grid engineering, robust financial modeling, and forward-looking policy engagement. For commercial buyers, developers, and policymakers alike, success hinges on viewing this investment through the lens of operational efficiency and guaranteed long-term return on investment (ROI).
Beyond the Charger: Understanding the Scope of EV Infrastructure Development in the Gulf
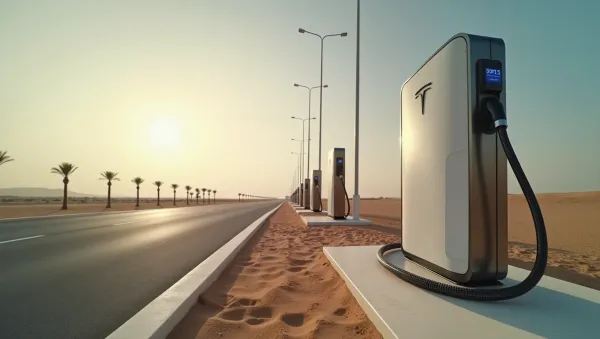
To approach EV infrastructure simply as installing an "electric vehicle charger" is to fundamentally misunderstand its complexity. From a commercial standpoint, this infrastructure must be viewed as a sophisticated, integrated energy asset that serves diverse operational needs—from last-mile logistics fleets operating within dense urban centers like Riyadh or Jeddah, to large industrial campuses in the Eastern Province.
The modern scope of development requires thinking about the entire ecosystem: power sourcing (often solar PV integration), distribution (transformers and feeder lines), storage (batteries), management software (load balancing, billing, user authentication), and physical hardware. When a developer plans for a new commercial compound or industrial asset, they must integrate this charging network from day one, ensuring that future scalability is budgeted into the initial design.
The regional market is actively maturing to meet this demand. The sheer scale of investment being directed at smart city developments means that infrastructure providers are rapidly professionalizing. For instance, major state-backed entities, such as the Electric Vehicle Infrastructure Company (EVIQ), a joint venture between the Public Investment Fund (PIF) and the Saudi Electricity Company (SEC), exemplify this institutional commitment within the Kingdom of Saudi Arabia. The formation of these dedicated bodies underscores that EV network building is now recognized by governments as a critical national utility function.
This centralized approach ensures standardization, which is paramount for private investment confidence. It allows commercial buyers to plan their energy consumption with greater certainty, whether connecting a corporate fleet or developing a mixed-use residential compound. The underlying assumption must be that reliable access to an "electric vehicle charging station" will be guaranteed and scalable.
Furthermore, the scope extends beyond passenger vehicles. We are seeing robust demand for solutions catering to commercial fleets. Analyzing the requirements for optimal two-wheeler options—used heavily in last-mile delivery across dense urban areas like Riyadh or Jeddah—requires a different charging profile and depot management strategy than servicing larger sedans.
Therefore, infrastructure development must be segmented by use case:
- Depot Charging (Fleet Management): High capacity, overnight bulk charging for commercial vehicles. Focus on minimizing downtime and maximizing utilization rates for logistics hubs.
- Public/Retail Charging: Designed for convenience and intermittent use in high-traffic areas or public parking garages. This is where the general "electric vehicle charger" model applies.
- Industrial Campus Charging: Integrated into larger facilities (e.g., manufacturing plants, logistics hubs near KAEC), often requiring integration with internal microgrids and 3-phase power sources to support heavy machinery alongside charging loads.
The Technical Backbone: Choosing Charging Levels and Managing Grid Load Capacity
From a purely engineering standpoint, the choice of charging level is not merely about speed; it dictates operational feasibility, required electrical service capacity, and ultimately, the total cost of ownership for the system. Understanding this technical backbone is non-negotiable for minimizing risk in challenging environments.
Understanding Charging Levels
The industry standard defines two primary commercial levels: Level 2 and DC Fast Charging (DCFC). The optimal deployment strategy requires matching the technology to the use case:
- Level 2 AC Charging (e.g., 7 kW - 19 kW): Ideal for predictable, lower-power charging scenarios. This is perfect for overnight depot charging or public parking garages where vehicles remain parked for several hours. From a utility perspective, Level 2 charges are generally easier to distribute and manage load on existing SEC feeder lines because the power draw rate is moderated over time.
- DC Fast Charging (DCFC) (e.g., 50 kW - 350 kW): Designed for maximizing energy transfer in minimal time. DCFC is crucial for highway corridors, public rapid-turnaround locations, and fleet charging where vehicles need to quickly replenish capacity before deployment into the Arabian Gulf’s major cities. For industrial loads requiring high burst power—such as heavy equipment needing temporary electric support—DCFC principles are adapted via dedicated commercial rectifiers.
A key takeaway for developers is that while DCFC offers maximum convenience, it demands significantly more robust infrastructure and sophisticated load management compared to Level 2 systems.
Grid Capacity Planning and Smart Integration
The greatest technical challenge in the Arabian Gulf’s rapidly expanding urban centers is not installing chargers; it is ensuring that local electrical distribution can handle simultaneous, high-power draws without necessitating costly grid upgrades. This requires moving beyond simple capacity estimates to implementing smart integration.
Grid planning must account for peak demand modeling. For a large industrial load, the total power draw (P) of multiple charging units running simultaneously is calculated using principles like P = V × I, but scaled up by complex load factors and diversity ratios. Smart charge management systems are essential tools that prevent localized overloading. They act as the central intelligence layer, dynamically throttling individual charger outputs to ensure that the combined demand remains within the local transformer or feeder line's safe operating limits.
Furthermore, regional infrastructure must be hardened against environmental extremes. The ambient temperatures across the Arabian Gulf are notoriously high, with summer peaks exceeding 50°C and compounded by fine desert sand and saline coastal air. Commercial-scale charging stations require specialized hardware—including advanced cooling solutions and industrial-grade components—to ensure reliable operation and longevity. Failure to account for thermal stress translates directly into operational downtime and significant maintenance costs.
This focus on resilience is particularly visible in mega-projects like those envisioned within NEOM, which mandate that all new infrastructure, including charging networks, must be designed with peak efficiency and minimal environmental impact from the outset. This proactive approach to grid stability elevates EV charging from a simple utility add-on to an integral component of the smart city's core energy resilience plan.
Making it Profitable: Business Models and ROI for EV Infrastructure Investment
For private capital, the investment thesis for EV infrastructure must be built around predictable revenue streams and quantifiable returns. The business model determines who owns the asset, how the power is managed, and how value is captured.
Analyzing Commercial Ownership Structures
Three dominant models structure profitability in this sector:
- Charge Point Operators (CPOs): These entities own, operate, and maintain the physical charging hardware. Their revenue comes directly from usage fees (per kWh or per session). Success depends on strategic location selection within commercial compounds and maximizing uptime.
- Energy Service Companies (ESCOs) / Developers: These partners integrate the charging network into a larger property development. They manage power procurement and distribution, treating the charging infrastructure as part of a bundled utility offering for tenants or residents in new villas or commercial towers.
- Utility Partnerships: The local electric utility (such as SEC) manages grid connection and load balancing, often partnering with CPOs to deploy hardware. This model offers high reliability but requires careful negotiation regarding revenue sharing and long-term operational control.
From an investment standpoint, the optimal structure often involves a blend: the developer owns the land/building (the asset), the ESCO manages the power connection and integration (risk mitigation), and the CPO handles the day-to-day charging experience (revenue generation).
ROI Drivers and Financial Mitigation
To calculate ROI, one must look beyond simply covering electricity costs. Key financial drivers include:
- Utilization Rate: The average percentage of time chargers are in use during peak operational hours. This is the single most critical operational metric for CPOs.
- Demand Charges Mitigation: By implementing smart load management, the system minimizes costly demand charges from the utility—a major risk mitigation factor.
- Ancillary Revenue Streams: Successful deployments often integrate charging into larger revenue-generating services (e.g., premium parking in shopping centers, or providing backup power during grid outages).
Furthermore, policy mechanisms significantly impact the financial viability. Policy makers and developers must understand how to navigate issues such as tax incentives for electric vehicle assets and what subsidies are available through national programs. These governmental levers can de-risk initial capital expenditure (CAPEX) for private investors.
The market is also highly focused on the total cost of ownership (TCO). For large fleet operators, choosing an appropriate energy source and managing charging cycles reduces operational expenditures (OPEX), making the overall investment in electric vehicle infrastructure far more attractive than continued reliance on fossil fuels. This applies equally whether discussing a standard car or analyzing the logistics potential of two-wheeler fleets for rapid city distribution.
Powering the Future: Integrating V2G and Policy Frameworks for Scalable Adoption
The most advanced stage of EV infrastructure development involves treating every vehicle not just as a consumer, but potentially as a mobile energy storage unit. This is where Vehicle-to-Grid (V2G) technology enters the strategic equation.
Vehicle-to-Grid (V2G) and Resilience
V2G allows electric vehicles to discharge stored energy back into the local grid or building microgrid when needed. From a national energy security perspective, this is transformative. During periods of high stress—such as extreme heat events or unexpected grid maintenance—the aggregated capacity of thousands of parked EVs can provide critical supplementary power, significantly boosting grid resilience.
This capability requires the integration of large-scale stationary storage batteries alongside the charging network. These battery energy storage systems (BESS) act as buffers, absorbing excess renewable generation (like midday solar peaks) and releasing it when demand spikes, thereby optimizing the use of intermittent clean power sources. This synergy is foundational to achieving true regional energy self-sufficiency.
For infrastructure investors, V2G capability exponentially increases the asset value of a charging hub because it provides revenue streams beyond simple kilowatt-hour sales—it offers grid stability services managed through advanced software that monitors both vehicle state-of-charge and local demand in real time.
The Policy Accelerator for GCC Adoption
Technology alone cannot guarantee scale; supportive policy is the ultimate catalyst. Rapid, sustainable rollout across the Arabian Gulf depends on clear regulatory frameworks addressing interconnection standards, standardized charging protocols, and market participation rules specific to KSA's grid operator (SEC) requirements.
Policy efforts must focus on several areas:
- Standardization: Mandating consistent hardware interfaces and communication protocols for all new commercial installations to prevent proprietary lock-in.
- Interconnection Rules: Streamlining the process by which private developers can connect high-capacity charging arrays (e.g., 3-phase power) to local distribution grids, reducing bureaucratic friction across cities like Jeddah and Dammam.
- Incentives: Developing clear policies that incentivize investment in specific sectors, such as mandatory EV readiness for all new commercial building codes or preferential access for electric heavy-duty trucks operating through industrial zones.
The commitment demonstrated by authorities launching initiatives like the build-out of a nationwide network of fast-charging hubs confirms this policy focus. The continued expansion of these networks—with plans to complete dozens of charging stations across major regional capitals—shows that governments are proactively de-risking the market for private capital.
Ultimately, understanding how electric vehicles work at a system level means recognizing that they are part of an integrated energy matrix. The seamless integration of renewable sources with optimized charging networks is critical to supporting everything from passenger cars to commercial needs like corporate fleet solutions in major Saudi compounds.
For those unfamiliar with the specifics, understanding general concepts, such as what constitutes a basic "electric vehicle charger," must be paired with an appreciation of its potential role in a sophisticated energy grid capable of operating reliably despite extreme ambient temperatures and dust challenges.
Key Takeaways
- Shift Focus: Investment must shift from merely installing chargers to integrating fully managed, smart microgrids capable of load balancing and incorporating renewable energy storage.
- Strategic Differentiation: Commercial viability requires matching charging technology (Level 2 vs. DCFC) precisely to the operational use case (depot vs. public rapid turnover).
- Future-Proofing ROI: Maximizing return involves positioning infrastructure for advanced technologies like V2G and BESS, transforming assets from simple chargers into grid resilience providers.
- Policy is Paramount: Successful scaling requires proactive policy frameworks that standardize technical protocols, simplify grid interconnection via SEC/SEWA channels, and incentivize private capital deployment across the Arabian Gulf region.
Related articles
- Choosing the Best EV Charging App for Electrified Roads in the Arabian Gulf
- Decoding Your Drive: A Guide to Choosing the Best EV Charging Network in the Arabian Gulf
- Electrifying Your Journey: A Guide to Choosing the Right EV for Life in the Arabian Gulf
- Powering Tomorrow: A Homeowner’s Guide to Electric Vehicle Charging in the Arabian Gulf
- Electric Mobility in Saudi Arabia: A Homeowner’s Guide to EV Charger Installation and Solar Integration
Explore topics: Ev Charging, Gulf, Renewable Energy
The information in this article is for educational purposes only. Always verify specifications, availability, and suitability with a qualified supplier or engineer before making purchasing or installation decisions.